Walk Your Property
After a storm, walk around the house and look for damage. Get more than one opinion, and don't sign with the first person who knocks on your door.

We photograph the damage, tell you plainly whether a claim is justified, and explain how it could play out. You stay in control.
The most common storm damage we see here is from wind and falling limbs. Here is what we do when it happens to you.
After a storm, walk around the house and look for damage. Get more than one opinion, and don't sign with the first person who knocks on your door.

The inspection is free. We get on the roof, fly the drone, and show you photos of what we found.
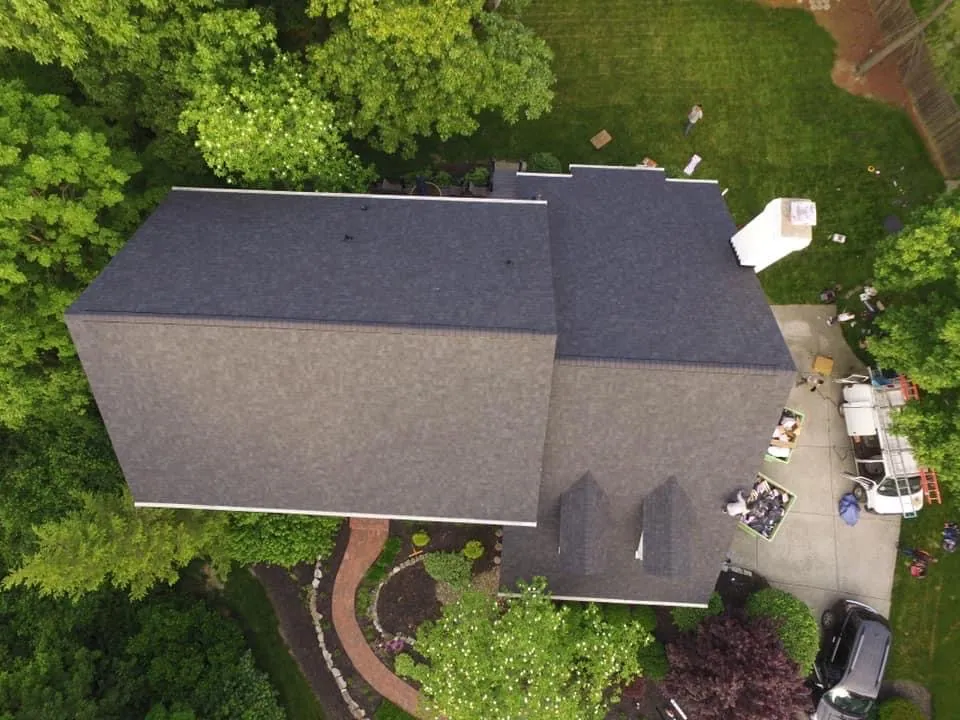
If the damage justifies a claim, we say so. If it's a small problem, we'll tell you that too and give you a repair price.

We explain how a claim could play out and back you up with our photos. The claim is yours, and it goes best when you stay involved.
What you do in the first day or two shapes a roof insurance claim more than anything that comes later. None of it is complicated.
If rain is coming in or a limb has opened the roof, that comes before any paperwork. Call (513) 528-0023 and ask about emergency roof tarping. Move what you can out from under the leak and put a bucket down.
Stay off the roof. Circle the house and photograph shingles in the yard, dented gutters, fallen branches and any stain indoors. Write down the date of the storm while you still remember it.
Crews you have never heard of tend to appear on the street right after bad weather. You're under no obligation to the first one. Have two or three companies look, and compare what each one shows you.
Read anything a contractor hands you before your name goes on it. A free inspection from us comes with no paperwork to sign.
Your deductible, your coverage and your deadlines are spelled out in your policy. Your agent is the person to read it with you. A roofer who offers to do that for you is overstepping.
This one distinction sits behind many of the roof claims that end in a disagreement, so we explain it to every homeowner who is weighing a claim.
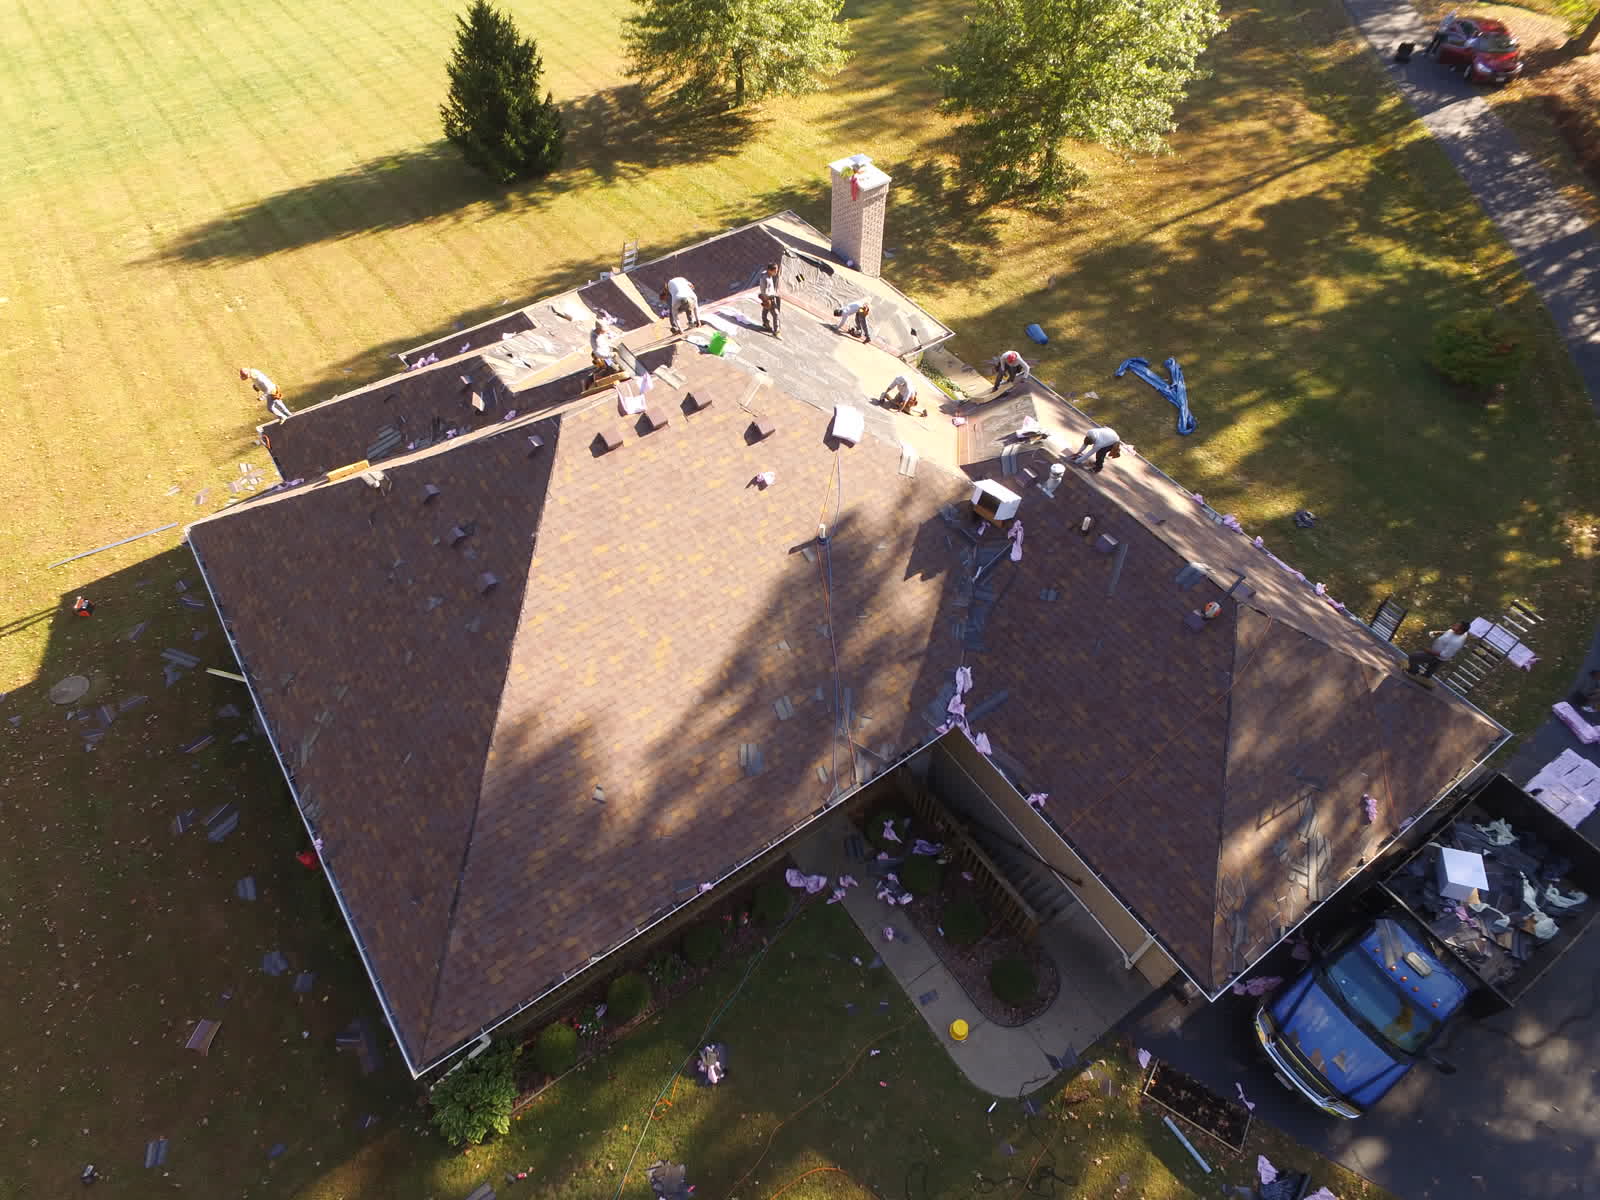
Suppose wind strips a section of your roof. An insurer may propose patching that section with a shingle that resembles yours. Resembling it and being it are different things. Manufacturers retire colors and whole product lines, and a shingle made last year will not blend with one that has weathered for fifteen.
When the original shingle can no longer be bought, the question becomes whether a patch truly puts the roof back the way it was. We can't answer that for your policy. What we can do is show, with an NTS report, whether a match exists.
A common sticking point is a damaged shingle that has been discontinued or can't be matched. When that happens, we can send a sample to NTS, a company whose business is identifying building products.
That gives you and your insurer evidence to work from. It doesn't guarantee an outcome, and if we don't think there's a case, we'll tell you.
An NTS report is the tool we reach for when a claim turns on whether your shingle can be matched. It replaces two guesses, ours and the adjuster's, with a finding from a company that identifies building products all day.
Only when there is real storm damage and the shingle looks discontinued or mismatched. If neither is true, we won't bring it up.
We pull a sample shingle off the roof and send it to NTS. NTS identifies it and reports back. We go over the report with you in plain language.
A report can turn a recommendation to patch into a justified full roof. It can also confirm that a patch is the right call, and we'll tell you if it does. It is evidence for you to bring to your insurer. It is not a promise of how they will rule.
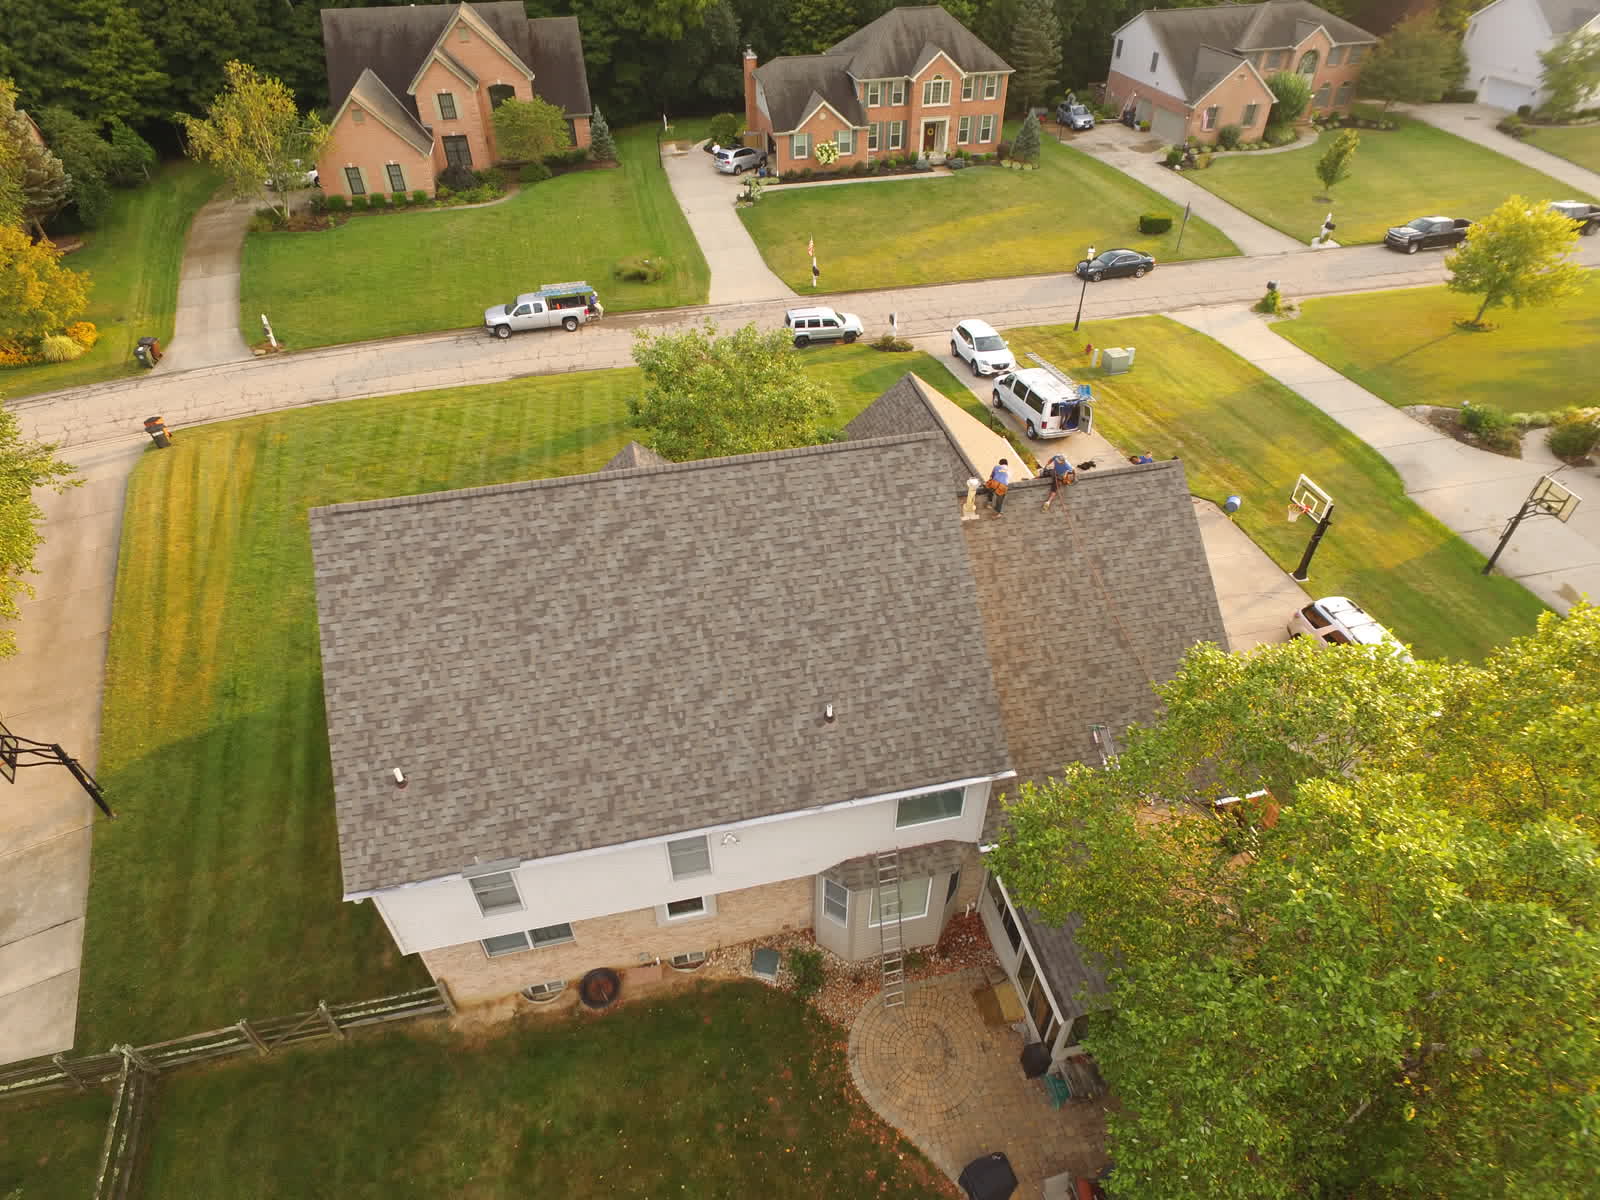
A few lifted shingles on a roof that is otherwise young is a repair job. We'll hand you a repair price and you can pay for it without opening a claim at all. On a problem that small, we may never bring up insurance.
When a claim is the right route, it goes best for homeowners who stay close to it. We bring the photos, the findings and the explanations. You make the calls to your insurer and speak up for your own house.
We can't promise that, and nobody honestly can. What we can do is show you the damage, tell you whether we think a claim is justified, and explain how it could go.
Often not. On a small issue with a newer roof, we probably won't even bring up insurance. We'll give you a repair price and let you decide.
Wind damage and damage from falling limbs. Hail damage is rare here.
Call us at (513) 528-0023. We offer emergency roof tarping. We tarp first, then diagnose, estimate and repair it properly.
We give you our photos, our findings and our advice, and we explain the scenarios. The claim itself is yours to manage, and questions about your policy go to your agent.
Yes. It costs nothing whether you file, pay for a repair yourself or do nothing.
It is wording found in many homeowners policies. How yours is written is something to go over with your agent. We explain the practical side: the gap between getting your own shingle back and getting one that only looks close.
The date of the storm, any pictures you took, and a way into the attic if the house has one.
Give us a call or fill out the form. We'll set up a free inspection and tell you where you stand.
Our office team is in Monday to Friday, 8AM to 5PM.
"*" indicates required fields
Two locations serving your community. Our office team is in Monday to Friday, 8AM to 5PM.
Main office
Start with a free inspection. You'll get photos of the damage and a straight answer.
Rated 4.9 on Google. Read our reviews